
In 2014, my father was diagnosed with Lewy body dementia, the second most common type of dementia after Alzheimer’s disease. My family had no idea how difficult the road ahead would be as we worked to get him the care he needed while the disease progressed. He passed away in 2017. As a financial advisor, I found comfort in being able to take the stress of managing my parents’ finances off my mother during that time.
My father never liked to ask for outside help with his personal finances. But a few years before his diagnosis, while he was still well enough to make his own decisions, he brought me down to his office in the basement to go over his accounts in case his health were to decline. At the time, I was a trader on Wall Street and knew very little about how a retiree should manage their finances. Knowing what I know now, this is what I wish I had told him that day:
- For your family’s sake, consolidate. The binder my father used to track his accounts was always accurate, but as I thumbed through the graph paper with numbers carefully penciled in, I noticed that over time the pages became less detailed and the entries further apart. I didn’t know it then, but this was one of the earliest signs of his cognitive decline. When his condition worsened and I took over the accounts, there were checking and savings accounts at several banks, CDs reinvesting at almost no interest, paper savings bonds with no record of them anywhere else, and a portfolio with very little direction. It was made up of investments collected over the years that were never revisited to see if they were still suitable. We consolidated those accounts and built a portfolio that reflected my parents’ needs, and my mother was able to see everything in one place online.
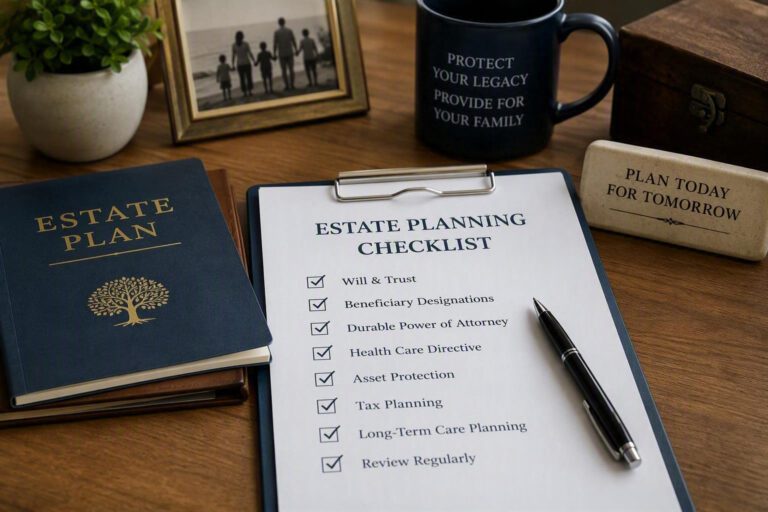
- Dust off those estate plans. It isn’t uncommon for a young family to set up an estate plan when they marry or have their first child and never revisit it. This is a mistake. I cannot emphasize enough how important it is to have a durable power of attorney with clear direction. The power of attorney was an essential tool in managing my father’s finances. His will and health care proxy took many of the most difficult decisions off our family’s shoulders. We were able to spend our time with him and focus on giving him the best quality of life we could, knowing what his wishes were.
- Long-term care isn’t cheap, so what’s the plan? The cost of long-term care can easily dwarf the cost of a four-year college education. A private room in a nursing home now averages around $10,800 a month nationally. We spend years planning how to pay for our children’s education, but very little time planning how we will pay to maintain our own quality of life in our later years. Long-term care insurance isn’t always feasible, but when it fits, it can be an extremely valuable tool. It should be considered sooner rather than later, because policies become more expensive as we get older. My father did not have a long-term care policy, and having one would have made the planning process easier.
- Can anyone help pay the bills? Beyond long-term care insurance, other ways to help cover the cost of care include Medicaid, VA benefits, and certain supplemental insurance policies. We explored all of these after my father was already sick, and in the early days it took time away from getting him the help he needed. Understand these programs before you need them so you know whether they will be available to you. Even if you are eligible, the paperwork can be overwhelming, and it is better to be prepared.
- Work with the pros. Talking to your children about your finances and your wishes is a great first step, but also give your family a team of professionals and their contact information so they can step in and do the heavy lifting when needed. A financial planner can act as the quarterback for your family, working with you and the other professionals you trust. I was fortunate to work with my family’s estate attorney and accountant, who guided me through the process. A geriatric social worker or elder care consultant can also be a valuable resource.
Nobody wants to think about the possibility of losing their cognitive abilities, but having a plan in place makes it far easier for your loved ones if they ever need to oversee your care. Reacting to unfortunate events leads to worse outcomes than planning for them. Take the initiative and speak with a qualified professional about your plan. I wrote more about protecting older adults from financial exploitation in My Day at the Fed.
Content in this material is for general information only and not intended to provide specific advice or recommendations for any individual.