
New York is one of only a handful of states that still has its own estate tax, and its rules are very different from the federal rules. Many of the families I work with in Westchester and the Hudson Valley will never owe federal estate tax, but they can still owe New York estate tax. Here is how it works in 2026 and what you can do about it.
New York and federal estate tax: two different systems
- Federal exemption: $15,000,000 per person in 2026, or $30,000,000 for a married couple. The One Big Beautiful Bill Act made this higher exemption permanent, and it will be adjusted for inflation in future years.
- New York exclusion: $7,350,000 per person in 2026.
- New York tax rates: graduated rates that reach 16% at the top.
Put simply, an estate worth $9 million is well under the federal exemption but well over New York’s. That gap is where most of the planning happens.
The New York “cliff”
New York’s exclusion does not work like the federal exemption. If your taxable estate is more than 105% of the exclusion amount, you lose the exclusion entirely and the whole estate is taxed, not just the amount over the limit. For 2026, 105% of the exclusion is $7,717,500.
That means an estate slightly under $7,350,000 owes no New York estate tax, while an estate of $7,800,000 is taxed on the full $7,800,000. Estates that sit near the cliff have the most to gain from planning.
No portability for married couples in New York
At the federal level, a surviving spouse can generally use any exemption the first spouse did not use. This is called portability. New York does not allow it. If everything passes outright to the surviving spouse, the first spouse’s New York exclusion can be wasted, and the combined estate may be taxed at the second death.
A common solution is a credit shelter trust (sometimes called a bypass trust) in each spouse’s estate plan. At the first death, assets up to the New York exclusion go into the trust, where they can still benefit the surviving spouse but are kept out of the survivor’s taxable estate.
Lifetime gifting
Giving assets away during your life reduces the size of your estate. In 2026 you can give up to $19,000 to as many people as you like without using any of your lifetime exemption. A married couple can give $38,000 per recipient. Contributions to a 529 college savings plan for a child or grandchild count toward this annual exclusion and are a popular way to move money out of an estate for a purpose you care about.
New York does not have a gift tax. However, it does have a three-year addback rule: taxable gifts made within three years of death are added back to the New York estate. This rule currently applies to estates of people who die before January 1, 2032. Gifts that fall within the annual exclusion are not taxable gifts, so they are not added back. Larger gifts made earlier, or made by someone in good health, can still reduce New York estate tax significantly.
Trusts that can help
- Revocable living trust: avoids probate and keeps your affairs private, but the assets are still part of your taxable estate. See Adding a Personal Backup With a Living Trust.
- Irrevocable trusts: assets you move into these trusts are generally removed from your taxable estate. You give up control in exchange for the tax benefit.
- Irrevocable life insurance trust (ILIT): life insurance owned by an ILIT is kept out of your estate, and the proceeds can give your heirs cash to pay estate taxes without selling a home, a business, or investments at a bad time.
Charitable giving and the cliff
For estates just over the cliff, a charitable bequest can make a large difference. Because the whole estate is taxed once you cross 105% of the exclusion, a gift to charity that brings the taxable estate back under the exclusion amount can save far more in New York estate tax than the gift itself costs your heirs. Your estate attorney can draft a clause that sizes the gift automatically based on the value of the estate at death.
Business owners and real estate
If much of your estate is a closely held business or real estate, liquidity becomes a concern. Succession planning, buy-sell agreements, and life insurance can help your family keep the business running and pay any tax that is due. Valuations matter here, so these plans should be revisited as the business grows.
Review your plan regularly
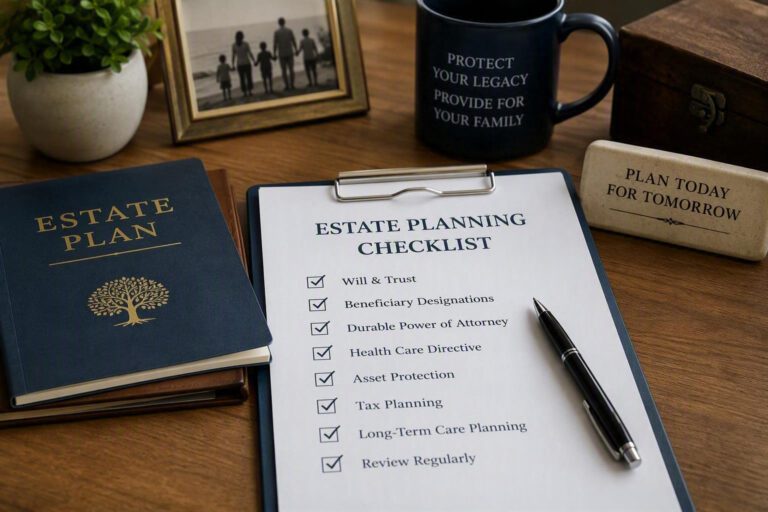
Estate tax rules change, and so do families. The federal exemption is now permanent, but New York’s rules are set separately by the state legislature, and your own net worth will move with markets and life events. I recommend reviewing your estate plan with your attorney and financial advisor every few years and after any major change. For a checklist of what to look for, see Five Estate Planning Mistakes Successful Families Make.
Content in this material is for general information only and not intended to provide specific advice or recommendations for any individual.